Investing in democracy

US midterms deliver a reminder of democracies’ advantages

Are democracies up to the challenge?

Last week’s US midterm elections were a powerful reminder of how swiftly democracies can deliver change. Many in the West, including committed democrats, lament that autocracies are better at making swift decisions, particularly on long-run, consequential problems. Yet democracies’ indecision often reflects due caution and best-ideas sorting in the face of Uncertainty; decisive action comes when and as needed. I have written a lot over the years about the challenge state capitalism poses to liberal capitalist democracy as a paradigm and how China, specifically, has leveraged state capitalism to challenge US hegemony over the last three decades. But perhaps surprisingly, the West’s political volatility and seeming disorder over the last decade — including last Tuesday — reaffirms my faith that democracies can meet the challenge. That’s important for more than just geopolitics; it likely matters far more for your investment portfolio than you may realize.

Lessons from nature

Nature’s crucible of evolutionary competition didn’t freeze when Homo sapiens sapiens first set foot upon the earth. The heat just shifted to competition between humans’ organizational systems: tribes, feudal orders, nations, and competitive political systems. Nature’s lessons still apply. While evolution is often taught as a battle for ruthless efficiency — the first tree to fill an opening in the forest canopy, the fastest gazelle or cheetah — exclusive focus on efficiency almost always is a genetic dead end. A moth that perfectly blends into its landscape becomes a visual archetype for birds; a rabbit taking the fastest path to its borrow gives a fox a predictable intercept path; or the strongest male lizard may be cuckolded by a sneaky rival while fighting.1[1] The solutions to all of these problems were solved by nature through genetic trial and error that often settled on inefficient solutions — randomized patterns and escape paths, mixed mating and survival strategies — that give both a leg up on the competition and boost survivability when the unexpected happens, like a comet hitting the earth. Competition between rival political systems is no different.

Where the mandarins’ genius ends

With impeccable timing, Francis Fukuyama called liberal capitalist democracy’s victory over all other political systems the “End of History” just in time for state capitalism to arise as a formidable new challenger.2[2] Within three decades, China rose from an impoverished, technologically backward land of bicycles to the world’s largest manufacturer, technological leader and the only real strategic competitor to the US. Yet, China’s rise was only possible due to the certainty Pax Americana provided. Without US guarantees for freedom of navigation, flow of capital and rules for trade, China’s miracle could never have happened. China’s leadership should be applauded for plotting a steady course when few others did, but their top-down design could only succeed amid the environmental certainty afforded by US hegemony. Set against the collapse of the post-War liberal order with a “Clash of Civilizations”3[3] impeding a new world order, accelerating technological progress upending social, political, economic, and military hierarchies, space emerging as the new frontier, and an unprecedented collapse in global birthrates, top-down planning is far less likely to succeed in the decades ahead.

And democratic chaos excels

As Mother Nature knows, chaotic, bottom-up adaptations excel in confronting the Uncertainty that challenges efficient, top-down planning. That has been democracies’ secret weapon on the battlefield from Salamis to Hiroshima, in trade from the Venetian and Dutch Republics to the US, and in technological leadership from Roman engineering to Silicon Valley.4[4] Democracies have repeatedly delivered innovative solutions to complex problems in large part because they are inefficient: America’s Congress dismissed General Horatio Gates in favor of Nathanael Greene midway through the Revolutionary War; Abraham Lincoln shuffled through several generals before settling on Ulysses S. Grant; the UK changed prime ministers in both world wars. And even democracies’ saviors like Themistocles and Winston Churchill will be cast aside once danger passes. To paraphrase a famous Churchill quote: democracies can be counted on to get it right, after they have tried everything else.

The ignorant voter myth

I know that some readers are rolling their eyes and retorting, “Voters in my country are too stupid to be trusted.” I have two responses to that, one moral and one factual. My moral response is “Fine, but please never again lecture anyone about democracy.” Few things irk me more than supposed defenders of democracy who don’t trust their fellow citizens to vote. If you don’t have faith in your compatriots to inform themselves and vote their interests without intervention, then you really don’t believe in democracy, so stop pretending otherwise. If you genuinely prefer autocracy or oligarchy, good for you for being honest.

Joe Six Pack has a strategy

My factual answer is that there’s a vast political science literature showing that voters are far better at informing themselves and voting their interests than is generally accepted. All Swiss cantons and 24 of 50 US states combine republican and direct democracy, i.e. elected representative government with the ability to enact laws through popular referenda. Researchers poring over thousands of referenda across decades, two countries, and dozens of jurisdictions with varying degrees of direct democracy consistently find that even on extraordinarily complex issues like insurance rules that even confuse industry lawyers, voters, on average, inform themselves sufficiently to vote their own interests.5[5] Through a “wisdom-of-crowds” aggregation of information across employers and coworkers, civic and religious organizations, friends and neighbors, they triangulate their own interests by judging supporters and opponents.6[6] Voters don’t need to become experts to make informed, self-interested decisions and that on average their errors cancel out. Remember that the next time your favorite news media interviews an ignoramus with a view they want you oppose but not the equal-and-opposite idiot from the next village.

And makes better choices than his leaders

What is even more astounding is that this literature shows that voters tend to make better laws than their elected leaders and that merely having the ability to do so improves their representatives’ lawmaking.7[7] The greater the degree of direct democracy across mixed jurisdictions, the lower are taxes and fiscal debts,8[8] the better are state services delivered,9[9] the higher are productivity, per capita income and economic growth,10[10] the happier are citizens with their governments, and the more trusting are they of their institutions.11[11] Indeed, because citizens are better at representing their own interest than elected representatives, researchers even find that laws passed by referenda are more stable and less subject to future change.12[12] Perhaps most fascinating — and counter to conventional wisdom — is that greater direct democracy leads to less redistribution of income than representative democracy.13[13] As if to emphasize that point, last week California voters rejected a ballot initiative imposing a billionaire tax with higher “no” proportions in rural and poorer counties.14[14]

Roots of Rage

A key finding from The Politics of Rage, the 22-country study of populism I wrote a decade ago,15[15] that people have the hardest time accepting is that income inequality is not an important driver of it. Across countries and political parties reviewed, I found instead that the primary source of popular rebellion was average voters’ sense that they had been disenfranchised by their governments and had lost sovereignty. The literature on mixed democracies reinforces my findings: given the opportunity, voters do not try to redress income inequality through redistribution nor do they undertake irresponsible spending. They are happy to let the richest among them be as long as everyone is equal in the voting booth. It is telling that the only OECD nation with a fully mixed democracy, Switzerland, is among the most fiscally sound, highest per capita income, highest productivity, happiest with their government, and has not experienced a significant populist backlash. Even more telling is that Swiss citizens report higher government and institutional satisfaction than expats living among them in the same circumstances because they are active participants in its creation.16[16]
Restless voters

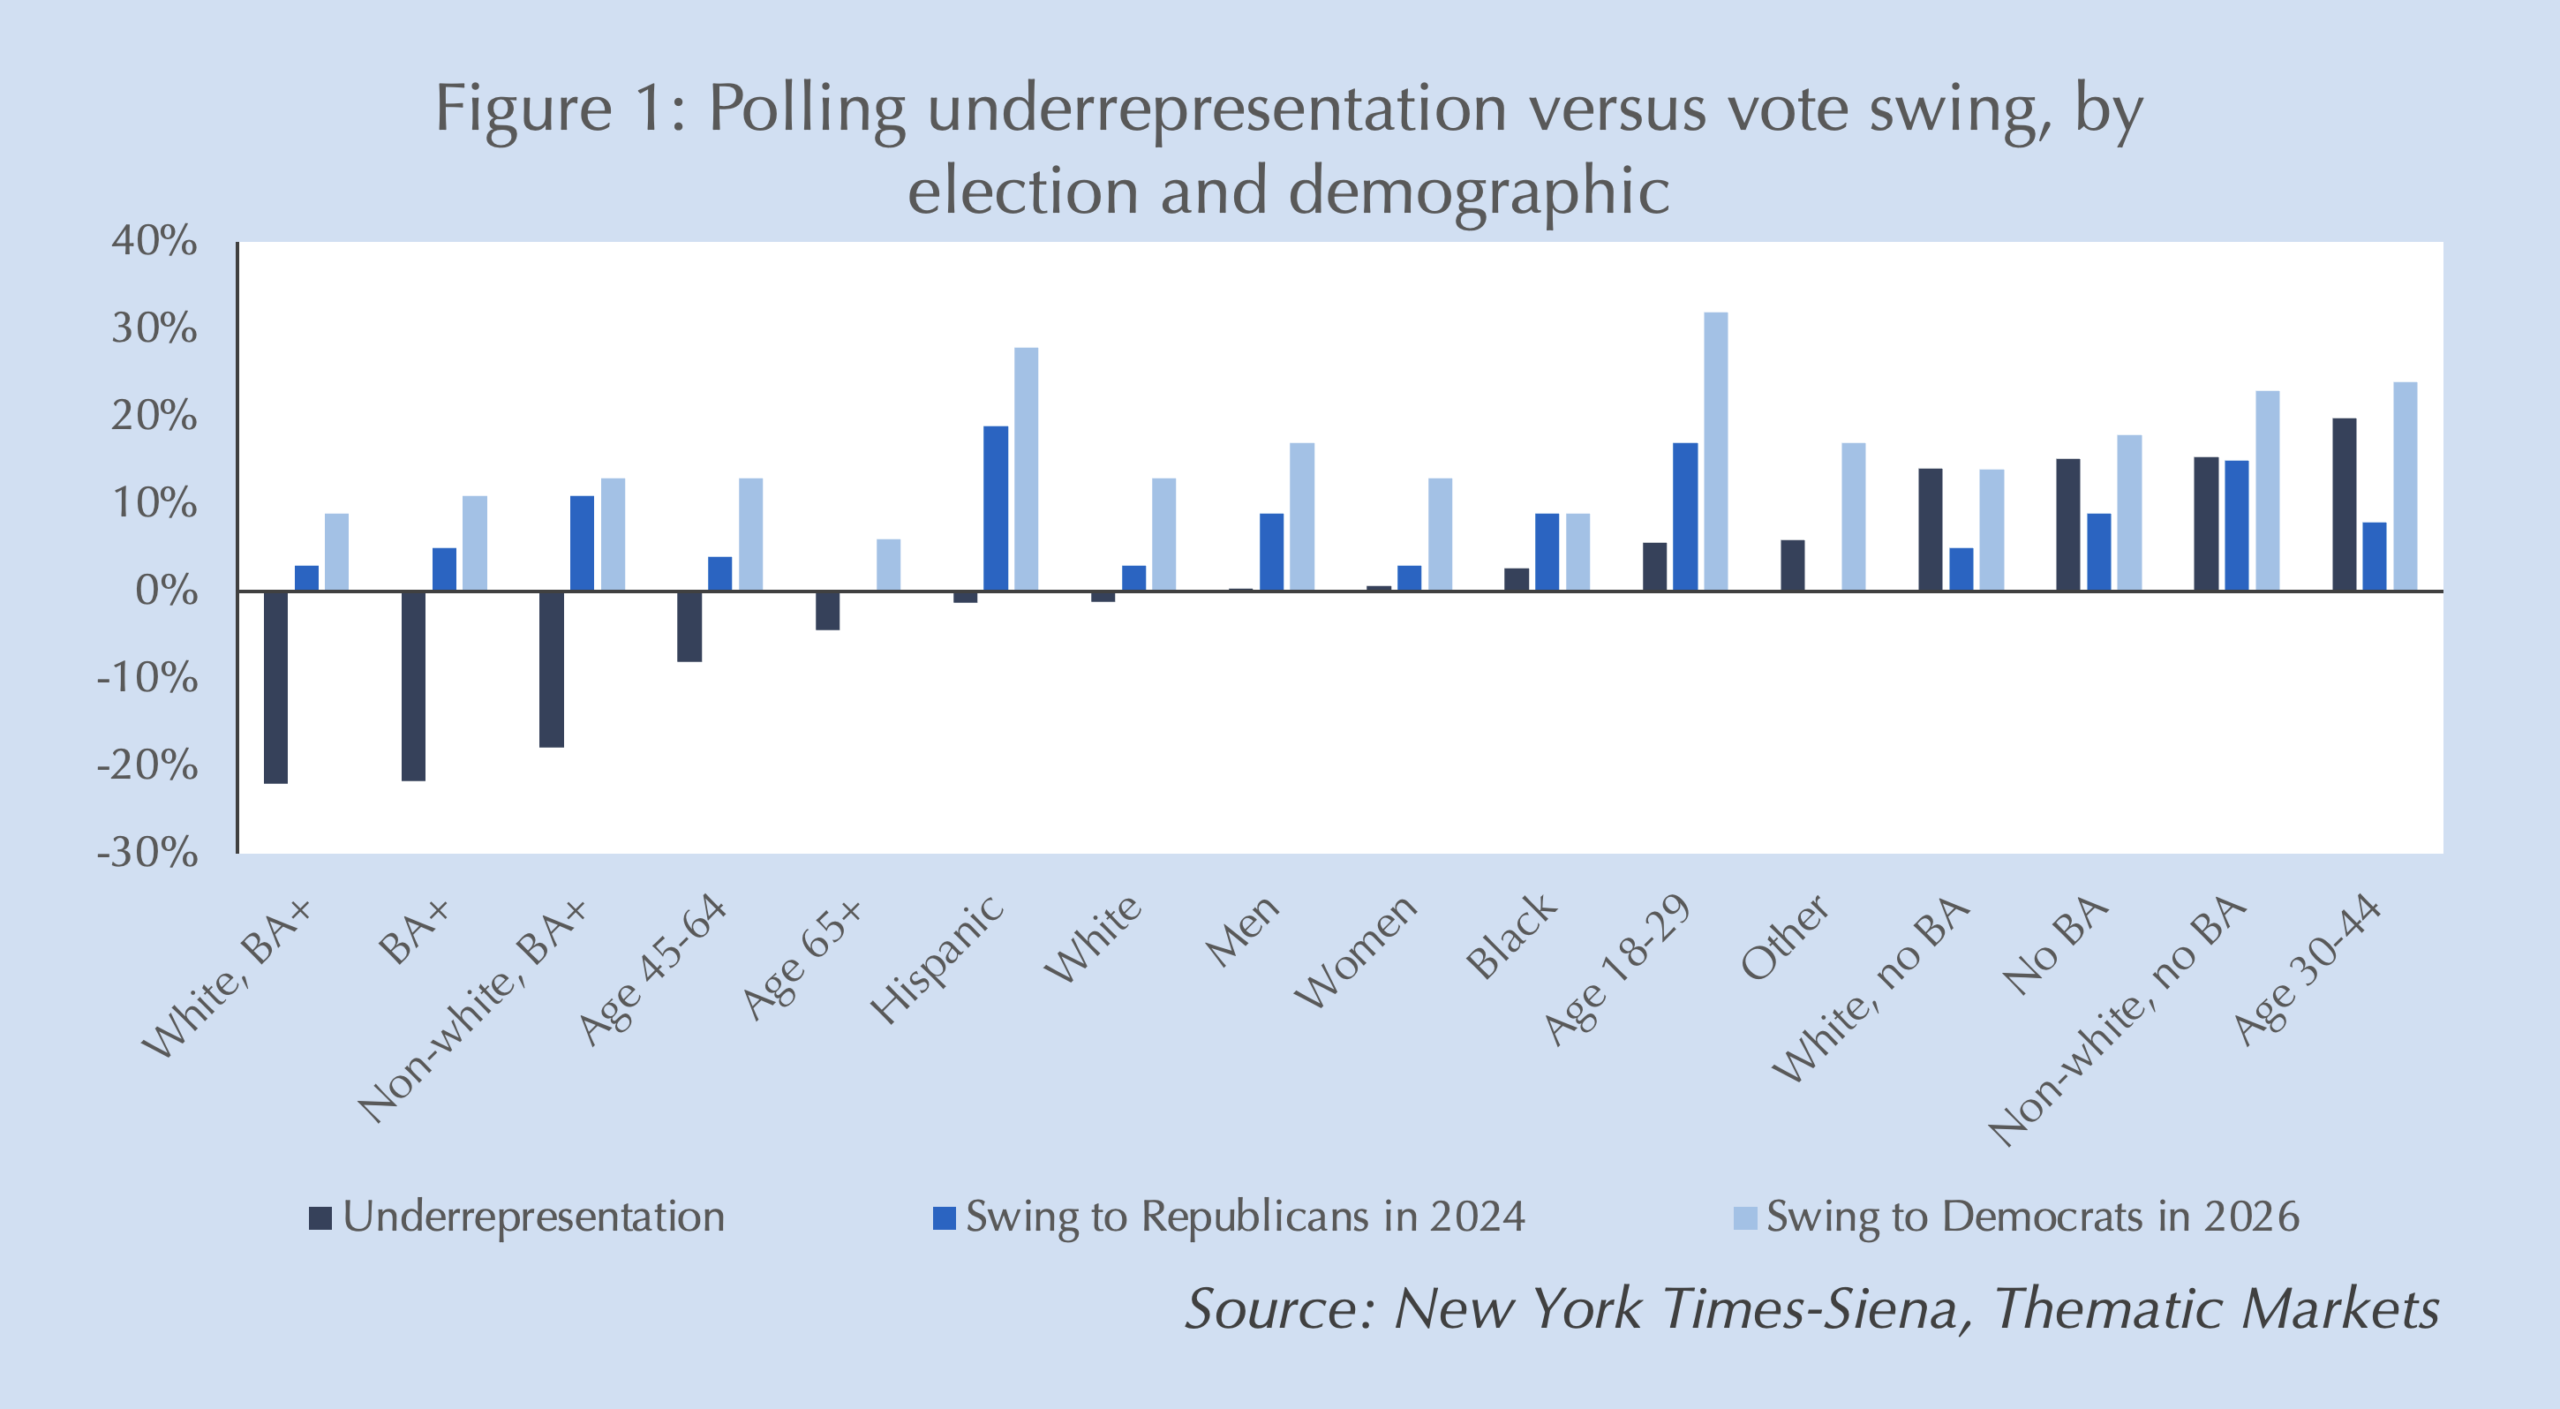
Most Westerners live in pure republican democracies, however. My point above is that voters are not as stupid (in aggregate) as many seem to believe, and can achieve similar results to mixed democracies in a sufficiently competitive pure representative democracy. That’s why I was encouraged by the US midterms. Figure 1 is reprinted from my election post mortem at Thematic Markets and shows the dramatic, back-to-back swings in voter preferences from 2020 to 2024 and from 2024 to 2026. Nearly all major demographics swung by double-digit percentages to Republicans in 2024 and away in 2026. As I discussed in the post mortem, it appears that many of the same disaffected voters who supported President Obama’s “Hope and Change” swung to and from President Trump over multiple elections.17[17] One of the things I got most wrong about this year’s election is that unlike 2012, when those voters sat out after losing their “hope” for “change,” many actively sought change. That’s a great sign for their increasing sense of power and the vibrancy of the US democracy.18[18]

Drive better representation

Research also shows that greater voter fluidity creates more responsive representative government,19[19] while party loyalties weaken responsiveness and enable corruption.20[20] This makes sense in the context of George Savile’s 17th century observation that “The best Party is but a kind of Conspiracy against the rest of the Nation.” The extent to which voters enable such conspiracies undermines both their own representation and national dynamism. Indeed, corrupt politics is a telltale sign of voter dissatisfaction: experimental research shows that voters’ tolerance for corruption increases with their sense that no alternatives exist.21[21] That government corruption was a top-two issue for voters according to exit polls last week is an extremely positive sign that US voters are beginning to feel that they have more agency.22[22]

Competing for votes

Both the Democratic and Republican Parties appear to be getting the message. Despite boiling partisan anger among the Democratic base, prospective Speaker of the House, Hakeem Jeffries, said after the election,“The American people don’t want us to get even. They want us to get things done on their behalf.”23[23] His sentiment was echoed by numerous newly elected and incumbent Democratic politicians.24[24] Republicans, too, began to frankly assess their failures and recalibrate their positions to better appeal to voters in 2028.25[25] Even President Trump suggested he was willing to work with Democrats to get legislation passed.26[26] I’m not naïve enough to think everyone will bury the hatchet and move on. Social media responses from both sides’ respective bases suggest that will be difficult. But the tone of Democrats, in particular, was distinctly different from their midterm election wins in 2006 and 2018 facing an unpopular Republican president.

Bullish on democracy

Given my small-c conservative preferences, it is unlikely that I will share many, if any positions with Representative Jeffries. But that’s not the point. His prospective Speakership testifies to a vibrant and competitive US democracy that likely will better respond to the heightened Uncertainty of our age. If he and his Democratic colleagues do not, in 2028 they will find themselves on the receiving end of the vote-switching that helped bring them to power in this election. Redistricting that backfired on Republicans this year makes Democrats just as vulnerable to swings in voter sentiment in two years.27[27] I am sometimes accused of being pro-populist but in reality I’m pro-democracy. All of my research into populism shows that its foundational issue is a demand for greater democratic accountability. A vibrant democracy bubbles up new ideas and lets the best win, solving complex problems better than any panel of experts.

Investable conclusions

While competition with China is a critical issue, this is about far more than just geopolitics. Societies are grappling with numerous unprecedented challenges from how to master AI rather than be mastered by it, to rapid aging amid collapsing births, to rising cultural tensions within and between nations; along with ancient challenges like debt sustainability and growing standards of living. These are exactly the problems that democracies solve better than alternative forms of government. But there also are investable conclusions. As I noted above, more competitive democracies produce better economic outcomes, higher productivity, better infrastructure, and more sustainable finances. Looking through last week’s rout of AI stocks and what are likely to be noisy and chaotic US politics for the foreseeable future, US political and economic dynamism is hard to deny. That is particularly true in relative terms. Not all democracies are equal in their dynamism as Europe demonstrates only too well. This will almost certainly reveal itself in sustained US outperformance until Europe and others begin to show the same electoral volatility the US is demonstrating.
[1] “Visual predators select for crypticity and polymorphism in virtual prey,” Alan B. Bond & Alan C. Kamil, Nature, vol. 415, 7 February 2002; “The rock–paper–scissors game and the evolution of alternative male strategies,” B. Sinervo & C. M. Lively, Nature, vol.380, 21 March 1996; and “Protean defence by prey animals,” D.A. Humphries & P.M. Driver, Oecologia, vol. 5, no. 4, December 1970. [2] The End of History and the Last Man, Francis Fukuyama, The Free Press, New York, 1992. [3] The rival (and correct) challenger to Mr. Fukuyama’s “End-of-History” thesis: The Clash of Civilizations and the Remaking of World Order, Samuel P. Huntington, Simon & Schuster, New York, 1996. [4] “Political Institutions and Output Collapses,” Patrick Imam & Jonathan Temple, CEPR Discussion Paper 19074, 14 May 2024; and “Democracy and Battlefield Military Effectiveness,” Dan Reiter & Allan C. Stam III, Journal of Conflict Resolution, vol. 42, no. 3, June 1998. [5] “Direct Democracy Works,” John G. Matsusaka, Journal of Economic Perspectives, vol. 19, no. 2, Spring 2005; and “Direct Democracy: New Approaches to Old Questions,” Arthur Lupia & John G. Matsusaka, Annual Review of Political Science, vol. 7, June 2004. [6] “The Institutional Foundations of Political Competence: How Citizens Learn What They Need to Know,” Arthur Lupia & Mathew D. McCubbins, Elements of Reason, Ed. Arthur Lupia, Mathew D. McCubbins & Samuel L. Popkin, 5 June 2012; and “Shortcuts versus encyclopaedias: Information and voting behavior in California insurance reform elections,” Arthur Lupia, American Political Science Review, vol. 88, no. 1, March 1994. [7] “Public Policy and the Initiative and Referendum: A Survey with Some New Evidence,” John G. Matsusaka, Public Choice, vol. 174, 22 November 2017. [8] Ibid; “Does Direct Democracy Reduce the Size of Government? New Evidence from Historical Data, 1890–2000,” Patricia Funk & Christina Gathmann, Economic Journal, vol. 121, no. 557, December 2011; For the Many or the Few: The Initiative, Public Policy, and American Democracy, John G. Matsusaka, University of Chicago Press, 2004; and “Budget Referendums and Government Spending: Evidence from Swiss Cantons,” Lars P. Feld & John G. Matsusaka, Journal of Public Economics, vol. 87, no. 12, December 2003. [9] “Private versus öffentliche muellabfuhr—Nochmals betrachtet,” Werner W. Pommerehne, Finanzarchiv, vol. 41,1983. [10] S. Brock Blomberg, Gregory D. Hess and Akila Weerapana, “The Impact of Voter Initiatives on Economic Activity,” European Journal of Political Economy, vol. 20, no. 1, March 2004; and “Direct Democracy Matters for Economic Performance: An Empirical Investigation,” Lars P. Feld & Marcel R. Savioz, Kyklos, vol. 50, no. 4, November 1997. [11] “Empowering the Principal: How Direct Democracy Shapes Trust in Institutions,” Fabian Kuhn & Benno Torgler, Public Choice, vol. 208, 17 March 2026; and “Happiness, Economy and Institutions,” Bruno S. Frey & Alois Stutzer, Economic Journal, vol. 110, no. 466, October 2000. [12] “Public Policy and the Initiative and Referendum: A Survey with Some New Evidence,” John G. Matsusaka, Public Choice, vol. 174, 22 November 2017; and “Direct Democracy Works,” John G. Matsusaka, Journal of Economic Perspectives, vol. 19, no. 2, Spring 2005. [13] “The Effect of Direct Democracy on Income Redistribution: Evidence for Switzerland,” Lars P. Feld, Justina A.V. Fischer & Gebhard Kirchgässner, Economic Inquiry, vol. 48, no. 4, 2010. [14] “Billionaire tax rejected on concern squeezing California’s ultra-rich would harm the economy,” Queenie Wong & Seema Mehta, The Los Angeles Times, 9 November 2026. [15] “The Politics of Rage,” Marvin Barth, Barclays Research, 23 October 2016; available to paid subscribers to Thematic Markets on request. [16] “Happiness, Economy and Institutions,” Bruno S. Frey & Alois Stutzer, Economic Journal, vol. 110, no. 466, October 2000. [17] “Not by Turnout Alone: Measuring the Sources of Electoral Change, 2012 to 2016,” Seth J. Hill, Daniel J. Hopkins & Gregory A. Huber, Science Advances, vol. 7, no. 17, 21 April 2021. [18] Hat tip to MDV, one of my institutional clients, who the day before the election speculated on this exact occurrence, i.e. that voters empowered by their success in bringing Donald Trump to power wouldn’t use that power to punish him when he failed them. [19] “Electoral Volatility and Parties’ Ideological Responsiveness,” Ruth Dassonneville, European Journal of Political Research, vol. 57, no. 4, November 2018. [20] “Democracy in America? Partisanship, Polarization, and the Robustness of Support for Democracy in the United States,” Matthew H. Graham & Milan W. Svolik, American Political Science Review, vol. 114, no. 2, 2020. [21] “Turning a Blind Eye on the Black Sheep: When Are Voters Loyal to Corrupt Politicians?” Michael Jankowski, Christina-Marie Juen & Marcel Lewandowsky, European Political Science, vol. 58, 2023. [22] “Blue-nami,” Carl M. Cannon, RealClearPolitics, 4 November 2026; “AP Voter Poll: How key demographic groups voted in the 2026 midterms,” PBS, 3 November 2026; and “2026 Exit Polls,” NBC News, 3 November 2026. [23] “Hakeem Jeffries: ‘The American People Don’t Want Us To Get Even. They Want Us To Get Things Done’,” video, RealClearPolitics, 4 November 2026. [24] “After taking control of Congress, Democrats vow major probes into Trump’s ‘tentacles of corruption’,” Seung Min Kim & Mary Clare Jalonick, Associated Press, 5 November 2026; “Democrats face a choice on Trump come January: Confrontation or compromise,” Alexei Koseff, Anna Liss-Roy, Mariana Alfaro, & Dan Merica, The Washington Post, 4 November 2026; “Texas Senate victor James Talarico lays out common ground with Trump, vows to ‘work together’,” Madison Colombo, Fox News, 4 November 2026; “Senator-Elect Adam Hamilton: ‘I’ll Be Deeply Disappointed’ If Democrats Spend The Next Two Years On ‘Investigations’,” video, RealClearPolitics, 4 November 2026; and “Democrat Roy Cooper’s victory speech after North Carolina Senate flip,” Reuters, 3 November 2026. [25] “Republicans hoping to succeed Trump in 2028 dissect midterm rout,” Ariana Baio, The Guardian, 5 November 2026; “Why did Republicans lose the midterm elections? GOP soul-searching begins after blowout.” Kaia Hubbard, CBS News, 5 November 2026; “‘Extinction-level event,’ ‘blue tsunami’: How Republicans eyeing 2028 are taking midterm losses,” Hannah Demissie, ABC News, 5 November 2026; Statement released on X, Vice President JD Vance, 4 November 2026; and “DeSantis Says Iran War Is ‘Big, Big Drag’ on GOP,” Alex Leary, The Wall Street Journal, 3 November 2026. [26] “60 Minutes Transcript: Donald Trump, the 2026 post-midterm elections interview,” Ross Douthat, Graham Messick & Andy Court, CBS News, 8 November 2026. [27] Texas, Florida, Ohio, North Carolina, Alabama, Louisiana, and Tennessee redistricted 5, 4, 2, and 1 each, respectively, to favor Republicans; while California and Utah redistricted 5 and 1, respectively, to favor Democrats. See “Redistricting ahead of the 2026 elections,” Ballotpedia, updated 5 November 2026.

Financial Disclosure and Disclaimer

The research, reports, and insights provided by Thematic Markets, Ltd are for informational purposes only and are not intended to constitute financial, investment, legal, tax, or other professional advice. The content is prepared without consideration of individual circumstances, financial objectives, or risk tolerances, and readers should not regard the information as a recommendation to buy, sell, or hold any specific securities, investments, or financial products.

Users of Thematic Markets, Ltd research are solely responsible for their own independent analysis, due diligence, and investment decisions. We strongly advise consulting qualified financial professionals or other advisors before making investment decisions or acting on any information provided in our materials.

The information and opinions provided are based on sources believed to be reliable and accurate at the time of publication. However, Thematic Markets, Ltd makes no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information. Markets, financial instruments, and macroeconomic conditions are inherently unpredictable, and past performance is not indicative of future results.

Thematic Markets, Ltd accepts no liability for any losses, damages, or consequences arising from the use of its research or reliance on the information contained therein. Readers acknowledge that investment decisions carry inherent risks, including the risk of capital loss.

This disclaimer applies globally and shall be enforceable in jurisdictions where Thematic Markets, Ltd, a company incorporated and based in England and Wales, operates. Readers in all jurisdictions, including but not limited to the United Kingdom, United States, Canada, European Union, Australia, Singapore, Japan, South Korea, and Taiwan, are responsible for ensuring compliance with local laws, rules, and regulations.

By accessing or using the research provided by Thematic Markets, Ltd, users agree to the terms of this disclaimer.

Comments are available to paid subscribers only.

Economic and market forecasts:

Economic & market forecasts
  • Sustained higher US rates, vulnerability of backend rates and term premia to steepening in H2 2023: Are we there yet?

  • No recession, continued strength of US economy throughout 2023: Solved: Drivers of the dollar cycle; Clash of the Themes; Are we there yet?; Opportunity knocks: Are you listening?; Götterdämmerung.

  • No backtracking or “pivot” by the Fed in 2023: Solved: Drivers of the dollar cycle; Clash of the Themes; Are we there yet?; Opportunity knocks: Are you listening?; Götterdämmerung.

  • No banking crisis or reversal by the Fed following the failures of Silicon Valley Bank: Did QE cause bank failures? Opportunity knocks: Are you listening?

  • No new “Plaza Accord” resulting from US dollar strength and Fed rate hikes in 2022: Plaza 2.0 bid, not offered.

  • No default by Nigeria before or in the aftermath of the 2023 national elections: Debt reality versus perceptions.

  • The continued fall in US real rates through the 2000s and early 2010s. Themes & framework: Mercantilism (with Chinese characteristics) and the associated $Bloc/Chinese co-prosperity sphere undermined the marginal product of capital in the US while simultaneously increasing non-US demand for US Treasuries.

  • Emerging market outperformance in the 2000s. Themes & framework: Mercantilism (with Chinese characteristics) drove both the development of the $Bloc/Chinese co-prosperity sphere and the commodity supercycle, while Apex neoliberalism supported institutional reforms that lowered EM risk premia, all of which encouraged foreign direct investment that raised productivity and led to rapid economic growth.

  • The end of emerging markets’ “original sin” and growth of EM local bond markets, a development supported by a G7 initiative that I led at the US Treasury. Themes & framework: The $Bloc/Chinese co-prosperity sphere provided a new stability in many EM exchange rates while institutional reforms undertaken by many as part of Apex neoliberalism lowered EM risk premia.

  • The Global Financial Crisis (albeit see admission of errors below). Themes & framework: Mercantilism (with Chinese characteristics) and $Bloc/Chinese co-prosperity sphere simultaneously increased incentives for debt finance in the US (as demand for “safe” USD bonds rose globally) while undermining US means of repayment as the US marginal product of capital in traded goods fell. Combined with poorly designed bank regulation that allowed banks to leverage themselves well beyond regulators’ intent (Apex neoliberalism), “complexity cascaded”.

  • The failure of QE to generate post-GFC inflation. Themes & framework: Believing is being: inflation expectations were stable to falling amid deleveraging and associated lethargic income growth, lowering real interest rates as nominal rates were pinned at the zero lower bound, and implying sustained weak money demand. Stuffing banks with more reserves changed none of those variables. As Keynes described seven decades earlier – in the absence of negative nominal rates – monetary policy at the zero lower bound is equivalent to “pushing on a string”.

  • The lack of effect of balance sheet runoff on interest rates. Themes & framework: Believing is being and portfolio theory rejected the then dominant “portfolio balance” theory of QE. QE was a credible commitment by central banks to keep rates on hold, suppressing expectations for future rates and thus the yield curve. This is why the “Taper Tantrum” had its largest effects on 3-5 year forward rates as expectations for rates hiked rose, while long-dated forward rates fell. Measures of long-dated term premia continued to fall as the Fed reduced its balance sheet.

  • Peak Chinese growth in 2011. Themes & framework: Mercantilism (with Chinese characteristics) led to unsustainable contributions of investment to GDP and a collapse in China’s marginal product of capital amid historically large debt to GDP, a phenomenon that peaked with China’s 50% surge in domestic credit in response to the GFC. Domestic funding of its debt trapped China within its own financial repression scheme, frustrating its efforts to unwind its $Bloc/Chinese co-prosperity sphere and internationalization the renminbi as a closed capital account is required to avoid savings flight and a collapse of the debt bubble. This self-funded debt bubble implies that losses from consequent overinvestment are “amortized” in the form of slower growth.

  • Emerging Market underperformance of the last decade (and likely future decade). Themes & framework: Institutional reform in EM peaked with US policy credibility before the GFC under Apex neoliberalism; China’s peak within Mercantilism (with Chinese characteristics) in 2011 and the associated end of the commodity supercycle ended the “pack” economic benefits of the $Bloc/Chinese co-prosperity sphere, while simultaneously the advent of Localization began to shift production back to advanced economies. Amid stagnating growth and backsliding reforms, EM FX and asset prices looked (and continue to look) overvalued and risk spreads remain too thin.

  • Falling USD reserve share in the 2000s and a rising share since peak China. Themes & framework: The massive reserve accumulation required to sustain undervalution of the $Bloc/Chinese co-prosperity sphere came to be seen as “sovereign wealth” that required diversification, rather than a liquidity store for crises, and led to a consequent fall in the USD share of reserves. Yet the greater financial openness and cross-border claims that accompanied the Apex neoliberalism necessarily implied a proportional increase in capital outflows in periods of risk aversion; i.e. historically large reserves were not as large as perceived in reality. As China and the $Bloc/Chinese co-prosperity sphere slowed after 2011, and Global entropy increased Uncertainty with attendant effects on risk aversion, emerging markets learned painfully in 2014 that reserves were neither excess nor sovereign wealth, but instead necessary liquidity, and that the USD’s safe haven properties were unparalleled.

  • Low and falling inflation throughout the 2010s. Themes & framework: Missingflation, the unexplained trend component of global inflation that had led to two decades of inflation overforecasting by economists, showed no signs of abating and seemed to be caused by a continued slide in inflation expectations (Believing is being) as central banks struggled with the zero lower bound. The end of the trend would require both for central banks to make more credible commitment to raise inflation in conjunction with a sustained positive inflation shock.

  • The (trend) bottoming of long-term US real rates, higher-than-expected peak in Fed funds rates and US equity outperformance in the last decade. Themes & framework: China’s peak in 2011 under Mercantilism (with Chinese characteristics) and the dissolution of the $Bloc/Chinese co-prosperity sphere ended the trend of falling US real rates they had created. But it wasn’t until Localization gathered sufficient steam – and the US private sector had deleveraged – that US openness and technological leadership sufficiently raised US returns to capital to support a rise in US real rates. The Trump administration’s political support (Politics of Rage) for Localization gave another nudge to US relative returns to capital, and Covid again accelerated these phenomena further (and likely more sustainably).

  • The capitulation of Saudi Arabia’s price leadership/management in 2014 in the face of surging US tight oil production leading to lower and more volatile crude oil prices. Themes & framework: The end of the commodity supercycle brought about by peak China under Mercantilism (with Chinese characteristics) paused relentless crude oil demand growth, allowing innovation and a business-friendly US regime to undermined Saudi Arabia’s price leadership with tight oil production. Cartel dynamics combined with Saudi Arabia’s long-run price maximization led to a collapse in Saudi-enforced OPEC discipline, and lower, more volatile crude oil prices.

  • Financial volatility’s shift to a lower median level with more frequent, shorter explosions during the last decade. Themes & framework: Rising Uncertainty in politics (Politics of Rage), geopolitics (Global entropy), technology (Localization), and policy (Missingflation) amid Complexity cascades shifted the relative shares of total risk away from quantifiable sources towards unquantifiable sources; the counter-intuitive implication of rising uncertainty is lower median volatility as active risk taking retreats in information lulls, with violent explosions of price activity when new information is revealed.

  • Persistence of post-Covid supply constraints and sustainable inflation supported by rearview-mirror central bank policies leading to a flip in the direction of Missingflation. Themes & framework: Covid simultaneously accelerated both the economic and political motivations for Localization, caused a permanent shift in the structure of global demand, and disrupted existing global supply chains. Short-run aggregate supply could not adjust to the jump in investment and shift in demand quickly enough, creating prolonged shortages and the need for prices to curtail demand. The associated cost-push inflation was all the spark needed to ignite Believing is being changes in inflation expectation driven by central banks’ backward-looking policies based on a lack of understanding of Missingflation.

  • The Fed’s post-Covid rate cycle would be more like 1994 than the post-2000 gradualist cycles (a call I made in early 2021). Themes & framework: The intent of the Fed’s FAIT policy always was to boost long-run inflation expectations by falling “behind the curve” on inflation. Yet their lack of understanding of the causes of Missingflation and insufficient faith in their own ability to generate Believing is being kept them focused on “fighting the last war” too long, allowing inflation to run too hot, too quickly. But contrary to market conventional wisdom, inflation is deeply politically unpopular in an aging society and no central banker wants to be remembered as failing to control inflation. Accordingly, the Fed (eventually) will react forcefully to contain the Believing is being genie they underestimated.

  • Consistent underperformance of European economy, assets and the euro since the Global Financial Crisis. Themes & framework: Relative to trend growth, Europe was more highly indebted than the US, yet European policymakers too long considered the GFC an “American problem”. Combined with Europe’s greater institutional rigidities and a reluctance to write down bad assets, it would take proportionately longer to achieve necessary deleveraging. China’s 2011 peak within Mercantilism (with Chinese characteristics) and the rise of Localization undermined all parts of Europe: the globalization-dependent South and China-dependent North, while inflexibility and low levels of technological innovation inhibit Europe’s ability to adjust to the new global economic order.

  • UK outperformance of consensus Brexit forecasts. Themes & framework: Consensus forecast for post-Brexit UK were based on three flawed assumptions (due to underappreciation of themes!). First, by ignoring emergent Localization, growth forecasts grounded in Apex neoliberalism wrongly assumed globalization would continue to be a major driver of economic growth. Second, the consensus failed to acknowledge the UK’s long-run structural competitiveness: world-leading universities providing a technological edge in Localization; and strong, enduring institutions offering safety and stability amid Global entropy and rising Uncertainty. Third, the consensus, ironically, ignored the largest driver of trade (by a wide margin) in their own models: “gravity”, or proximity to trading partners. Network effects are extraordinarily powerful in trade and difficult to overcome.

  • Importance and implications for markets of Scottish independence referendum in 2014. Themes & framework: As one of the earliest manifestations of the Politics of Rage and its demands for greater political representation, the Scottish referendum was an unanticipated shock to markets and one of the first signs of Global entropy and the Uncertainty to come.

Global entropy

Manifest and growing disorder

By ignoring the endogeneity of complex systems and Rodrick’s globalization trilemma – that democracy, national self-determination, and economic globalization cannot enduringly coexist – Apex neoliberalism sowed the seeds of its own demise, leading to today’s manifest and growing global disorder: the end of Post-World War II international rules, rising ethnonationalism, multipolarity, the Politics of Rage, and the unwinding of globalized supply chains. In short, Huntington’s Clash of Civilizations trumped Fukuyama’s End of History. Apex neoliberalism facilitated rising trade-to-income ratios, cross-border capital flows, intergovernmental cooperation, and intra-economy income inequality; while simultaneously lowering financial spreads, inter-economy income inequality, and inter-state warfare. Global entropy likely will reverse many of these effects.

Missingflation

Economists don’t understand inflation

What are economists missing about inflation? In the two decades before Covid, market analysts, academic economists and central banks consistently overforecast inflation; in the last two years they have persistently underforecast it. Enduring one-way errors are not “white noise”; they demonstrate bias and strongly suggest that economists’ current understanding of inflation is flawed. Demographics, globalization and technology help to explain some of the forecast miss, but significant omitted variable bias remains, most likely due to failure to explicitly incorporate Believing is being.

Believing is being

Self-fulfilling beliefs are real

Beliefs drive everything from asset bubbles, to debt dynamics, to crypto currencies’ values, to inflation and hyperinflations (probably Missingflation, too). Good economists understand this but often omit beliefs from models to simplify because of the difficulty in measuring beliefs. Unfortunately, too many bad economists copy those models without understanding the potential for omitted variable bias. The rapid social, technological, political, and geopolitical changes behind Global entropy and Uncertainty are swiftly shifting beliefs, driving a feedback loop of economic and political outcomes. Yet the infrequency of these deviations and difficulty in measuring them make statistical modeling nearly impossible. Only through economic theory and full-spectrum information collection can we infer when and how beliefs are adjusting and their likely effects.

Complexity cascades

Complex systems fail unpredictably

Human societies, nation states and (especially) economies are examples of complex systems. Complex systems always operate in “broken” mode and ironically are more structurally stable when they have lots of small failures. But when they are subjected to massive or cascading shocks, complex systems can fail unpredictably and totally. Covid and manifest Global entropy represent self-reinforcing mammoth shockwaves that imply systemic collapses – in all spheres, socio-political, geopolitical, economic, and financial – are more likely than the consensus admits.

Uncertainty

Not all risks can be quantified

All risks are not the same. Some are quantifiable, like the chance of being dealt an ace in a game of cards. Others are not but can be subjectively guessed, like the chance you leave a casino a winner. Then there is uncertainty, the most dangerous of all risks because it is by definition, non-quantifiable: what is the chance the casino gets hit by a meteor? Apex neoliberalism created a façade of quantifiable risks; Global entropy and Complexity cascades are illustrating that the world is far more uncertain. The quantitative models in finance, business, economics, and politics that gained dominance during Apex neoliberalism generally have performed poorly as Global entropy has become more pronounced, a trend that is likely to sustain as uncertainty rises further. Scenario analysis and “satisficing” are the only proven frameworks for dealing with uncertainty.

Politics of Rage

The proletariat want their franchise back

Four decades ago, globalization and increasing economic returns to intellectual capital opened a fissure between elites and everyone else, especially in more developed economies. The economic and political consequences of Apex neoliberalism widened this fissure into a chasm of mistrust that has resulted in the political turmoil that engulfed most advanced economies in the last decade. Contrary to conventional wisdom, its causes derive more from perceived and actual political disenfranchisement than economic distress and inequality. Trends in the former suggest the wave is not near cresting, implying sustained socio-political, geopolitical and economic disruptions.

$Bloc/Chinese co-prosperity sphere

FX herding cures “fear of floating”

The “co-prosperity sphere” of bloc managed exchange rates centered around Chinese trade and the US financial system, alternatively known as Bretton Woods II or Chimerica, dramatically reoriented global supply chains, supported emerging markets’ financial development and economic boom of the 2000s, drove much of the dollar’s 2002-’11 depreciation, and ultimately likely caused the Global Financial Crisis. Emerging market crises of the late 1990s marked the final chapter in the Bretton Woods exchange rate system. Yet “Fear of floating” persisted until China’s Mercantilism and contemporaneous accession to WTO provided an alternative: exchange rates managed by “herd” or by “pack”. Hiding within the herd provided financial stability for China’s EM trading partners, while simultaneously allowing them hunt as a pack for foreign direct investment and supply-chain dominance. The size and rapid growth of the co-prosperity sphere distorted the global economy like a massive stellar object warps space-time. Collective suppression of exchange rates and domestic cost of capital diverted supply chain growth into the bloc, while attendant reserve accumulation led to a surge in demand for “safe” core economy bonds. The former undermined returns to capital in traded goods production outside the bloc and the latter depressed interest rates on “safe” US debt, encouraging overinvestment in non-traded goods like housing. (Note: I labeled this phenomenon “the dollar bloc” when I first wrote about it in 2003-04, but later referred to it as “the co-prosperity sphere”.)

Mercantilism (with Chinese Characteristics)

State capitalism’s unintended costs

China’s 1994-2012 “miracle” that lifted nearly a billion people out of poverty and its current growth problems both originate in its extreme application of the mercantilist “Asian growth model” originated by Japan and later copied by Asia’s “Tigers”. A combination of capital controls, protectionism, domestic financial repression, and industrial policy direct underpriced capital to favored industries that promote rapid capital accumulation and development by leveraging external demand (and technology) from advanced economies. Rapid development and convergence comes at cost, however. Underpriced capital and exchange rates lead to distortive overinvestment. Those losses are realized either abruptly and painfully through write downs – like those enforced on late-‘90s Asian Crisis economies by the IMF – or, if the economy can self fund, are “amortized” as lost future growth. Japan’s lost decade and China’s current funk are examples of the amortization path of economic loss.

Apex neoliberalism

Liberal capital democracy’s pyrrhic victory

Rapid global growth, particularly in the less developed world, “hyperglobalized” production and the growth of inter-governmental coordination derive substantively from the triumph of neoliberalism that followed the collapse of its ideological competitors with the Soviet Union’s fall and emerging market crises of the 1990s. But so too did the seeds of its undoing: The Politics of Rage, Mercantilism (with Chinese characteristics), Missingflation, and ultimately Global entropy. Rapid adoption of Western economic institutions and trade mechanisms followed from neoliberalism’s victory, promoting a world of hyperglobalization: ever-more dispersed but integrated global supply chains, just-in-time industrial processes with reduced redundancy, unfettered cross-border capital flows, and uniform rules that increased the influence of international institutions, non-governmental organizations and multinationals at the expense of local political control and less-skilled citizenry. Resultant uniformity and coincident digitization created a façade of certainty and quantification, promoting an overreliance on quantitative methods in decision processes, risk control and forecasting.

Economic and market phenomena:

Economic & market forecasts
  • The continued fall in US real rates through the 2000s and early 2010s. Themes & framework: Mercantilism (with Chinese characteristics) and the associated $Bloc/Chinese co-prosperity sphere undermined the marginal product of capital in the US while simultaneously increasing non-US demand for US Treasuries.
  • Emerging market outperformance in the 2000s. Themes & framework: Mercantilism (with Chinese characteristics) drove both the development of the $Bloc/Chinese co-prosperity sphere and the commodity supercycle, while Apex neoliberalism supported institutional reforms that lowered EM risk premia, all of which encouraged foreign direct investment that raised productivity and led to rapid economic growth.
  • The end of emerging markets’ “original sin” and growth of EM local bond markets, a development supported by a G7 initiative that I led at the US Treasury. Themes & framework: The $Bloc/Chinese co-prosperity sphere provided a new stability in many EM exchange rates while institutional reforms undertaken by many as part of Apex neoliberalism lowered EM risk premia.
  • The Global Financial Crisis (albeit see admission of errors below). Themes & framework: Mercantilism (with Chinese characteristics) and $Bloc/Chinese co-prosperity sphere simultaneously increased incentives for debt finance in the US (as demand for “safe” USD bonds rose globally) while undermining US means of repayment as the US marginal product of capital in traded goods fell. Combined with poorly designed bank regulation that allowed banks to leverage themselves well beyond regulators’ intent (Apex neoliberalism), “complexity cascaded”.
  • The failure of QE to generate post-GFC inflation. Themes & framework: Believing is being: inflation expectations were stable to falling amid deleveraging and associated lethargic income growth, lowering real interest rates as nominal rates were pinned at the zero lower bound, and implying sustained weak money demand. Stuffing banks with more reserves changed none of those variables. As Keynes described seven decades earlier – in the absence of negative nominal rates – monetary policy at the zero lower bound is equivalent to “pushing on a string”.
  • The lack of effect of balance sheet runoff on interest rates. Themes & framework: Believing is being and portfolio theory rejected the then dominant “portfolio balance” theory of QE. QE was a credible commitment by central banks to keep rates on hold, suppressing expectations for future rates and thus the yield curve. This is why the “Taper Tantrum” had its largest effects on 3-5 year forward rates as expectations for rates hiked rose, while long-dated forward rates fell. Measures of long-dated term premia continued to fall as the Fed reduced its balance sheet.
  • Peak Chinese growth in 2011. Themes & framework: Mercantilism (with Chinese characteristics) led to unsustainable contributions of investment to GDP and a collapse in China’s marginal product of capital amid historically large debt to GDP, a phenomenon that peaked with China’s 50% surge in domestic credit in response to the GFC. Domestic funding of its debt trapped China within its own financial repression scheme, frustrating its efforts to unwind its $Bloc/Chinese co-prosperity sphere and internationalization the renminbi as a closed capital account is required to avoid savings flight and a collapse of the debt bubble. This self-funded debt bubble implies that losses from consequent overinvestment are “amortized” in the form of slower growth.
  • Emerging Market underperformance of the last decade (and likely future decade). Themes & framework: Institutional reform in EM peaked with US policy credibility before the GFC under Apex neoliberalism; China’s peak within Mercantilism (with Chinese characteristics) in 2011 and the associated end of the commodity supercycle ended the “pack” economic benefits of the $Bloc/Chinese co-prosperity sphere, while simultaneously the advent of Localization began to shift production back to advanced economies. Amid stagnating growth and backsliding reforms, EM FX and asset prices looked (and continue to look) overvalued and risk spreads remain too thin.
  • Falling USD reserve share in the 2000s and a rising share since peak China. Themes & framework: The massive reserve accumulation required to sustain undervalution of the $Bloc/Chinese co-prosperity sphere came to be seen as “sovereign wealth” that required diversification, rather than a liquidity store for crises, and led to a consequent fall in the USD share of reserves. Yet the greater financial openness and cross-border claims that accompanied the Apex neoliberalism necessarily implied a proportional increase in capital outflows in periods of risk aversion; i.e. historically large reserves were not as large as perceived in reality. As China and the $Bloc/Chinese co-prosperity sphere slowed after 2011, and Global entropy increased Uncertainty with attendant effects on risk aversion, emerging markets learned painfully in 2014 that reserves were neither excess nor sovereign wealth, but instead necessary liquidity, and that the USD’s safe haven properties were unparalleled.
  • Low and falling inflation throughout the 2010s. Themes & framework: Missingflation, the unexplained trend component of global inflation that had led to two decades of inflation overforecasting by economists, showed no signs of abating and seemed to be caused by a continued slide in inflation expectations (Believing is being) as central banks struggled with the zero lower bound. The end of the trend would require both for central banks to make more credible commitment to raise inflation in conjunction with a sustained positive inflation shock.
  • The (trend) bottoming of long-term US real rates, higher-than-expected peak in Fed funds rates and US equity outperformance in the last decade. Themes & framework: China’s peak in 2011 under Mercantilism (with Chinese characteristics) and the dissolution of the $Bloc/Chinese co-prosperity sphere ended the trend of falling US real rates they had created. But it wasn’t until Localization gathered sufficient steam – and the US private sector had deleveraged – that US openness and technological leadership sufficiently raised US returns to capital to support a rise in US real rates. The Trump administration’s political support (Politics of Rage) for Localization gave another nudge to US relative returns to capital, and Covid again accelerated these phenomena further (and likely more sustainably).
  • The capitulation of Saudi Arabia’s price leadership/management in 2014 in the face of surging US tight oil production leading to lower and more volatile crude oil prices. Themes & framework: The end of the commodity supercycle brought about by peak China under Mercantilism (with Chinese characteristics) paused relentless crude oil demand growth, allowing innovation and a business-friendly US regime to undermined Saudi Arabia’s price leadership with tight oil production. Cartel dynamics combined with Saudi Arabia’s long-run price maximization led to a collapse in Saudi-enforced OPEC discipline, and lower, more volatile crude oil prices.
  • Financial volatility’s shift to a lower median level with more frequent, shorter explosions during the last decade. Themes & framework: Rising Uncertainty in politics (Politics of Rage), geopolitics (Global entropy), technology (Localization), and policy (Missingflation) amid Complexity cascades shifted the relative shares of total risk away from quantifiable sources towards unquantifiable sources; the counter-intuitive implication of rising uncertainty is lower median volatility as active risk taking retreats in information lulls, with violent explosions of price activity when new information is revealed.
  • Persistence of post-Covid supply constraints and sustainable inflation supported by rearview-mirror central bank policies leading to a flip in the direction of Missingflation. Themes & framework: Covid simultaneously accelerated both the economic and political motivations for Localization, caused a permanent shift in the structure of global demand, and disrupted existing global supply chains. Short-run aggregate supply could not adjust to the jump in investment and shift in demand quickly enough, creating prolonged shortages and the need for prices to curtail demand. The associated cost-push inflation was all the spark needed to ignite Believing is being changes in inflation expectation driven by central banks’ backward-looking policies based on a lack of understanding of Missingflation.
  • The Fed’s post-Covid rate cycle would be more like 1994 than the post-2000 gradualist cycles (a call I made in early 2021). Themes & framework: The intent of the Fed’s FAIT policy always was to boost long-run inflation expectations by falling “behind the curve” on inflation. Yet their lack of understanding of the causes of Missingflation and insufficient faith in their own ability to generate Believing is being kept them focused on “fighting the last war” too long, allowing inflation to run too hot, too quickly. But contrary to market conventional wisdom, inflation is deeply politically unpopular in an aging society and no central banker wants to be remembered as failing to control inflation. Accordingly, the Fed (eventually) will react forcefully to contain the Believing is being genie they underestimated.
  • Consistent underperformance of European economy, assets and the euro since the Global Financial Crisis. Themes & framework: Relative to trend growth, Europe was more highly indebted than the US, yet European policymakers too long considered the GFC an “American problem”. Combined with Europe’s greater institutional rigidities and a reluctance to write down bad assets, it would take proportionately longer to achieve necessary deleveraging. China’s 2011 peak within Mercantilism (with Chinese characteristics) and the rise of Localization undermined all parts of Europe: the globalization-dependent South and China-dependent North, while inflexibility and low levels of technological innovation inhibit Europe’s ability to adjust to the new global economic order.
  • UK outperformance of consensus Brexit forecasts. Themes & framework: Consensus forecast for post-Brexit UK were based on three flawed assumptions (due to underappreciation of themes!). First, by ignoring emergent Localization, growth forecasts grounded in Apex neoliberalism wrongly assumed globalization would continue to be a major driver of economic growth. Second, the consensus failed to acknowledge the UK’s long-run structural competitiveness: world-leading universities providing a technological edge in Localization; and strong, enduring institutions offering safety and stability amid Global entropy and rising Uncertainty. Third, the consensus, ironically, ignored the largest driver of trade (by a wide margin) in their own models: “gravity”, or proximity to trading partners. Network effects are extraordinarily powerful in trade and difficult to overcome.
  • Importance and implications for markets of Scottish independence referendum in 2014. Themes & framework: As one of the earliest manifestations of the Politics of Rage and its demands for greater political representation, the Scottish referendum was an unanticipated shock to markets and one of the first signs of Global entropy and the Uncertainty to come.

Foreign exchange forecasts:

Foreign exchange forecasts
  • The dollar’s trend fall 2002-’11. Themes & framework: The effects of the $Bloc/Chinese co-prosperity sphere on relative returns to capital, balance of payments and the effects of “diversification” as sovereign reserves evolved into sovereign wealth.

  • The dollar’s trend turn in 2011, surge 2014-2016, and counter-consensus strength in 2018 and 2021 (I was the only sell-side analyst to forecast USD strength in 2021). Themes & framework: The same forces driving the US real rates higher in the last several years – the end of Mercantilism (with Chinese characteristics) and its associated $Bloc/Chinese co-prosperity sphere, disproportionate benefit to the US from accelerating Localization, Global entropy and Complexity cascades, all played out in the USD, too, with added support from increased safe haven demand for the greenback due to rising Uncertainty brought about by Global entropy and Complexity cascades.

  • The euro’s plunge from $1.36 in mid 2014 to $1.05 in early 2015. Themes & framework: Reluctant deleveraging from the Global Financial Crisis combined with the sharp deterioration in European returns to capital following China’s peak within Mercantilism (with Chinese characteristics) and the shift to Localization from globalization implied a sharply lower real value of the euro. When ECB President Draghi ruled out the deflationary (1990s Japan) path to devaluation with his commitment to “whatever it takes”, Believing is being implied an immediate and massive change in the nominal value of the euro was required as the expected path for domestic prices flipped.

  • The yen’s surge from above 120 per dollar to below 105 in H1 2016. Themes & framework: Abenomics’ biggest success was its Believing is being commitment to reflate Japan’s economy, leading to a sharp depreciation of the nominal yen as expected future deflation was unwound. But yen depreciation included an “overshoot” to compensate for the risks that inflation might overshoot. The Bank of Japan’s tacit admission that “Quantitative & Qualitative Easing” could not create sufficient inflation with its December 2015 adoption of negative interest rates implied a rapid unwind of the overshoot given the yen’s deep undervaluation as beliefs shifted again.

  • The pound sterling’s pre-EU referendum fall to $1.40, post-referendum floor near $1.20, and its post-Brexit rebound above $1.30. Themes & framework: A steep risk premium in sterling was required to compensate for the Uncertainty induced by the Politics of Rage driven jolt. Yet, 1.20 represented a 60+ year low in purchasing power parity and seemed to undervalue the UK’s long-run structural assets – strong institutions, top global universities, leading tech industry – all of which were appreciating in value in a world of Localization, Global entropy, broader Uncertainty, and rising potential for Complexity cascades.

Political forecasts:

  • Political instability in Russia and China in 2023: Clash of the Themes.

  • Brexit 2016. Themes & framework: The chasm between elites (including those in markets) and ordinary citizens over the latter’s sense of disenfranchisement, the fundamental cause of the Politics of Rage, was clear well before the referendum and strongly suggested that bias in polling turnout models could fully account for the polls’ projected margin of defeat.

  • Trump 2016. Themes & framework: Record pre-election postal votes from registered independents (for whom no party seeks to “get out the vote”) suggested that, as with Brexit, the Politics of Rage’s disenfranchised and unaccounted for voters would be sufficient to overcome the (narrow) projected margin of loss.

  • Marine Le Pen’s 2017 success in reaching the run-off but ultimate failure to win French presidency. Themes & framework: The Politics of Rage framework suggested an undercounting of both Le Pen and left-wing populists’ support, giving her a clear path to the second round. But her projected margin of loss in the general election was far too large to be due solely to turnout bias, implying no chance of second-round success, particularly with left-wing populist voters dropping out or shifting support to Macron.

  • Trump narrow loss, post-election conflict 2020. Themes & framework: Pollsters’ mistaken focus on education levels as the source of their 2016 turnout errors rather than on (mis)trust driven by the Politics of Rage implied polls still were biased. Large shifts in minority voters towards Trump and unusually high “undecided” voters late in a highly polarized election also suggested the magnitude of Trump’s outperformance would be large (indeed, it was larger than 2016). But the margin to overcome also was much wider in 2020, suggesting a close loss by Trump. Increasing polarization and mistrust on both sides implied a violent reaction by a minority, whichever side lost.

Admission of errors:

I get things wrong, too, but hopefully am the wiser for it. This list is far from complete, but represents some of the ones that both stung and taught me the most.

  • Failing to specify financial institutions as at risk from credit trauma in 2023. While I did highlight that the most predictable source of for 2023 would be credit events following the massive rise in interest rates in 2022 (Debt reality versus perceptions), I didn’t specifically identify banks and other financial institutions as especially vulnerable, which proved to be the case with the failure of a few regional US banks in March 2023. Lessons learnt: Sometimes one’s focus on the underlying causes blinds to the obvious consequences, and levered entities with broad exposure will always be at risk from any traumas within an economy, even if sector or region specific.

  • Not seeing the Global Financial Crisis sooner. I saw the GFC earlier than many, but the extent of the financial system’s capital shortfall eluded me far longer than it should have. At the US Treasury from 2006 through early 2008 I was responsible for assessing foreign financial risks (sadly, institutional territorialism prevented an integrated approach with my domestic-side colleagues that may have focused more attention on off-balance-sheet financing of US housing). I chaired meeting after meeting in 2006-‘07 with market professionals, academics, regulators, and other policymakers where a noisy minority of participants argued that historic levels of debt to GDP implied an impending crisis. Yet when I challenged them to explain a channel of transmission, what would be the tipping point, why it had not occurred already, or to present evidence that bank capital was insufficient to absorb even an historic drop in US housing prices, none – including some who have become very famous for “calling” the GFC – could do so. Ultimately, it was the behavior of banks in funding markets in mid-to-late 2007 that clued me in that banks’ capital bases might not be what they purported (or, equivalently, contingent liabilities off balance sheet were far larger than people understood). What I had not done – nor, apparently had any of the “experts” I consulted in those years – was the detailed micro-level analysis that the protagonists of The Big Short had done (kudos to them). Lessons learnt: 1. “Macro” analysis often requires “micro foundations”; 2. many people claim expertise, don’t rely on it without evidence; and 3. notwithstanding (2), even if they can’t explain it, pay attention when a gathering minority claim to smell smoke. (Implicit lesson 4: don’t assume that the left hand is talking to the right hand in any organization.)

  • Losing my nerve at the bottom of markets in 2009. My framework helped me to correctly call the bottom in credit markets in January 2009 and recommend to the distressed debt fund I then worked for that we aggressively buy leveraged loans. But on market research mission in late February, I got spooked by US Treasury and Fed officials I met in New York and Washington. Throwing my framework out the window, on 6 March 2009, the exact day the S&P 500 hit its 666 low, I wrote a memo urging the fund to sell SPX futures as a hedge on its market exposure. Lessons learnt: 1. Never abandon your framework; and 2. don’t assume someone’s position or pedigree alone gives them an informational or analytical advantage: demand reasons and evidence.

  • Missing the euro’s partial rebound in 2017; indeed, I forecast it lower! I failed to acknowledge the extent of the uptick in economic activity, and importantly, the credit growth that the ECB’s “anything it takes” policy was generating. This one stung as I was a strong believer in then-President Mario Draghi’s approach and had previously highlighted credit expansion as a key metric of success. Lessons learnt: Keep your eyes on the ball and regularly check to see if any of the ex ante conditions established for changing your mind have been met.

  • Dollar weakness in summer 2020. Another one that really stings. Having correctly forecast that Covid-induced Uncertainty would lead to a surge in the USD as everyone scrambled for high-quality assets and liquidity in March-April 2020, I then failed to incorporate the unwind of that flight to quality as risk tolerance returned once the panic subsided. Lesson learnt: Sadly, the same as 2017 dollar lesson: Keep your eyes on the ball and mind your pre-established conditions for turning points.

  • I completely missed the Fed’s mini easing cycle in 2019. While we will never know and Covid eviscerated my chance at redemption, I still believe the Fed’s easing was not merited and likely would have necessitated more aggressive hiking later had the Covid crisis not intervened. The US economy continued to grow strongly in 2019, investment held up, and while headline inflation moderated somewhat, bottlenecks were generating rapid acceleration in a number of CPI subcomponents. But even if I was right on the economy, the FOMC sets policy and I failed to listen to them, particularly the increasing support for average inflation targeting. Lessons learnt: Policymakers set policy, listen to them even if you think they’re wrong.

  • Underestimating Jeremy Corbyn in the 2017 UK general election. I expected a small Conservative victory based on then Prime Minister Theresa May’s outreach to the working class and the Labour Party’s anti-Brexit tone. What I failed to notice was that Mr. Corbyn’s grass-roots campaign cleverly focused on local bread-and-butter issues and greater political devolution, directly addressing one of the primary drivers of the Politics of Rage: a widening sense of political disenfranchisement among the average citizenry. Corbyn’s tangible policies and outreach – which he largely abandoned in his losing 2019 campaign – easily trumped Ms. May’s intangible rhetoric as “hidden” Brexit voters didn’t trust her. Lessons learnt: Again, “macro” analysis needs “micro foundations”, particularly in politics; ignore at your own peril.

  • Texas Governor Rick Perry to win the 2012 Republican nomination and beat President Barack Obama in the general election. The foundations of the Politics of Rage were already well apparent by the 2012 election and Rick Perry’s campaign was well tuned to court the rising sense of disenfranchisement of working-class voters, particularly in Appalachia, and increasing distrust of institutional expertise across voters. Many of those voters were Democrats who were disappointed with the lack of “Hope and Change” promised by President Obama, making him vulnerable to any Republican who could attract a significant number of Democratic voters. Governor Perry’s bigger challenge appeared to be winning the Republican nomination, but his solid conservative credentials and popularity in the second-largest state suggested he would eek it out. Who knew he would self-immolate in a nationally televised debate? Lessons learnt: Themes are important – Trump proved the Politics of Rage four years later – but idiosyncratic risks always are present.